

Form 1116 allows U.S. expats to claim a Foreign Tax Credit for income taxes paid or accrued to another country. For most expats living in countries with tax rates similar to or higher than those in the United States, the credit eliminates U.S. income tax on the same income and prevents double taxation.
The FTC may not eliminate the entire U.S. tax liability when the foreign tax rate is lower or when certain foreign taxes do not qualify for the credit. It also cannot be used to reduce U.S. self-employment tax.
Who Needs to File Form 1116?
Most U.S. expats must file Form 1116 to claim the Foreign Tax Credit for income taxes paid to another country. This includes expats claiming the credit for taxes paid on foreign employment or self-employment income.
A limited exception applies when all your foreign-source income is passive income, such as interest or dividends. You may claim the credit without filing Form 1116 if:
- All your foreign-source income is passive-category income;
- The income and foreign taxes are reported on qualified statements, such as Forms 1099-INT, 1099-DIV, Schedule K-1, Schedule K-3, or qualifying substitute statements; and
- Your total creditable foreign taxes do not exceed $300, or $600 if married filing jointly.
If you have foreign salary or self-employment income, you cannot use this exception because not all your foreign-source income is passive. You must file Form 1116 to claim the credit.
Taxpayers who use the exception also cannot carry unused foreign taxes into or out of that tax year.
What Are the Main Benefits of the Foreign Tax Credit?
For most expats who pay income tax in a country with tax rates similar to or higher than those in the United States, the Foreign Tax Credit eliminates U.S. income tax on the same income.
Unlike the Foreign Earned Income Exclusion, the FTC does not remove foreign earnings from the U.S. tax return. This can preserve eligibility for the Additional Child Tax Credit and allow foreign earnings to count as compensation for IRA purposes. Unused foreign taxes may also be carried to another tax year.
Can You Claim the ACTC With the Foreign Tax Credit?
Claiming the Foreign Tax Credit may preserve eligibility for the Additional Child Tax Credit because the foreign earned income remains reported on the U.S. return.
For 2025, the standard ACTC calculation equals 15% of earned income above $2,500, subject to the unused Child Tax Credit and the refundable limit of $1,700 per qualifying child.
However, filing Form 2555 prevents you from claiming the ACTC. This applies even if you exclude only part of your foreign income or have other earned income that was not excluded.
The FTC preserves eligibility, but you must still meet the ACTC income, Social Security Number, and qualifying-child requirements.
Related: Additional Child Tax Credit for U.S. Expats
Can You Contribute to an IRA While Claiming the FTC?
Foreign salary and self-employment income generally continue to count as compensation for IRA purposes when you claim the Foreign Tax Credit.
Income excluded on Form 2555 generally does not count as IRA compensation. However, any earned income that remains taxable after applying the FEIE may still support an IRA contribution.
Whether a traditional IRA contribution is deductible depends on your income, filing status, workplace retirement-plan coverage, and the applicable annual limits. Roth IRA contributions are also subject to separate income limits.
The IRS IRA contribution guide explains which income counts as compensation.
Is the Foreign Tax Credit Better Than the FEIE?
For expats living in countries with tax rates similar to or higher than those in the United States, the Foreign Tax Credit is often more beneficial than the Foreign Earned Income Exclusion. The credit normally eliminates U.S. income tax on the same income without removing that income from the U.S. tax return.
The FTC can also preserve eligibility for the Additional Child Tax Credit, allow foreign earnings to count as compensation for IRA purposes, and create credits that may be used in other tax years.
The FEIE may be more beneficial for expats living in countries with no personal income tax or significantly lower tax rates. The correct choice depends on your income, foreign taxes, family circumstances, and long-term filing position.
Related: Foreign Earned Income Exclusion vs. Foreign Tax Credit: which one is better?
There are other limitations on certain foreign taxes that you cannot claim as a foreign tax credit. For example, the Foreign Tax Credit doesn’t apply against any tax paid to North Korea, Iran, Sudan or Syria.
Ready to simplify your U.S. tax questions? Schedule a 20-minute consultation with our tax expert today!
Book your spot here.
How to qualify for the Foreign Tax Credit?
- The tax must be actual foreign tax liability and legally derived
- The tax must be imposed on you
- You must have paid or accrued the tax, and
- The tax must be an income tax or Tax in Lieu of Income Tax
The Foreign Tax Credit is designed to prevent double taxation on the same income earned abroad and taxed by both the U.S. and a foreign country.
Following Foreign Taxes That Do Not Qualify:
- Taxes refundable to you
- Taxes subsided you or someone related to you
- Taxes you could have avoided paying as they are not required by law
- Withheld foreign taxes on dividends for foreign stocks and they don’t meet required minimum holding periods
- Withheld foreign taxes on gains and income from other foreign properties that don’t meet required minimum holding periods
Tax Tip 1
If you were using Foreign Earned Income Exclusion and then decided to revoke it, you can’t use it again for another 5 years. But if you use the Foreign Tax credit, you can revert to the FEIE.
One of the multiple benefits of Foreign Tax Credit (Form 1116) is that it doesn’t require additional information. So you don’t have to submit details about housing, visa type held in the foreign country, or your travels and duration of stay in the U. S. Another advantage is that to claim Foreign Tax Credit, you don’t need to pass any of the residence tests as opposed to the Foreign Earned Income Exclusion which requires applicants to pass the Bona Fide Residence Test or Physical Presence Test
What Is a Foreign Tax Credit Carryover?
A carryover is created when the qualifying foreign taxes paid on a particular type of income exceed the maximum Foreign Tax Credit you can use for that income during the year.
This commonly happens when an expat lives in a country with a higher tax rate than the United States.
Unused foreign taxes are generally carried back to the previous tax year first. Any amount that cannot be used in that year can then be carried forward for up to ten years.
Carryovers must be tracked separately for different types of income. For example, unused foreign taxes on salary cannot be combined with unused foreign taxes on interest or dividends.
Related: Foreign Tax Credit Carryover and Carryback Explained
Which Income Categories Are Reported on Form 1116?
Most U.S. expats use one or both of these Form 1116 categories:
- General-category income: Usually includes wages, salaries, and other employment income.
- Passive-category income: Usually includes interest, dividends, rents, and royalties.
A separate Form 1116 is normally prepared for each category. Foreign taxes paid on income in one category generally cannot be used to offset U.S. tax on income in another category.
Other categories may apply if you operate a foreign business, own a foreign corporation, use a tax treaty to re-source income, or receive certain other types of foreign income.
How to calculate the foreign tax credit and fill out Form 1116? (Example)
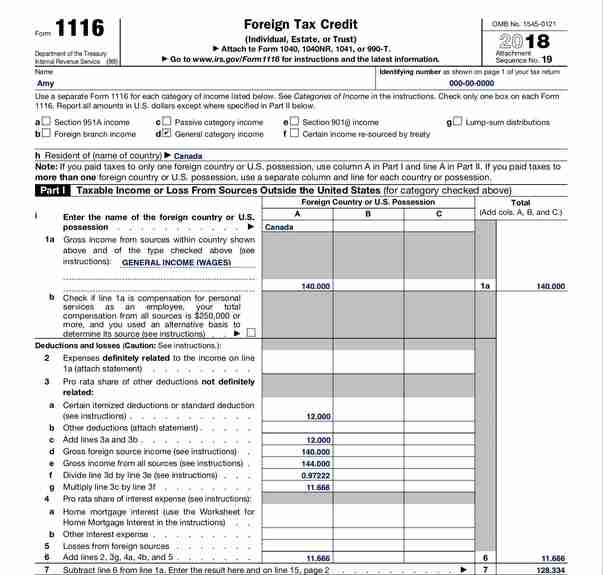
Amy is an American living in Canada. She had $140,000 of employment income and $4000 of income in dividends. Amy will use the advantage of the standard deduction that’s $13,850 for single filers in 2023. She has paid $29,602 tax for her wages and $722 tax for the dividend income. She does not claim itemized deductions.
Note: The amounts are shown in United States Dollars. Since the income comes from two different sources (General and Passive Category type of Income), Amy has to file two Foreign Tax Credit Forms 1116. One form for general category income and one form for the passive category income.
You cannot combine multiple categories of income and make the calculations using only one Form.
Step 1. Choose income category
Start by choosing the appropriate income category at the top of the form, (in case of the wages, check the box “general category income” and for investment income, check the box “passive category income”).
Passive Category Income includes interest, dividends and other investment income. Then, choose the taxpayer’s country of residence on the line H (in Amy’s case the country of residence will be “Canada”).
Step 2. Complete Part I
Here you need to report the income and name of the foreign country. Columns A, B, and C stand for multiple countries in which a taxpayer could earn income (in our first Foreign Tax Credit Form 1116, we will have only Canadian sourced wages under column A, as general type of income. You will need to do the same thing for the second form 1116).
From line 2 to line 5, the gross income from all sources is being reduced with deductions that relate to that foreign income (i.e. standard deduction which is $12,400 in the tax year 2021, for single taxpayers, or itemized deductions, if any). Deductions and losses related to exempt or excluded income such as Foreign Earned Income Exclusion cannot be reported here.
Line 3f explains the proportion of General Income with the Total Income, so we could know the amount of standard deduction which is attributable to General Income. The same method will be used when computing the numbers for Passive Category Income, in our second form 1116.
Line 3g represents the amount of standard deduction which is attributable to the specific income (In Amy’s case, she will have $11,666 of her standard deduction tied to her general income, while the rest will be tied to the passive income).
Step 3. Complete Part II. Paid or Accrued
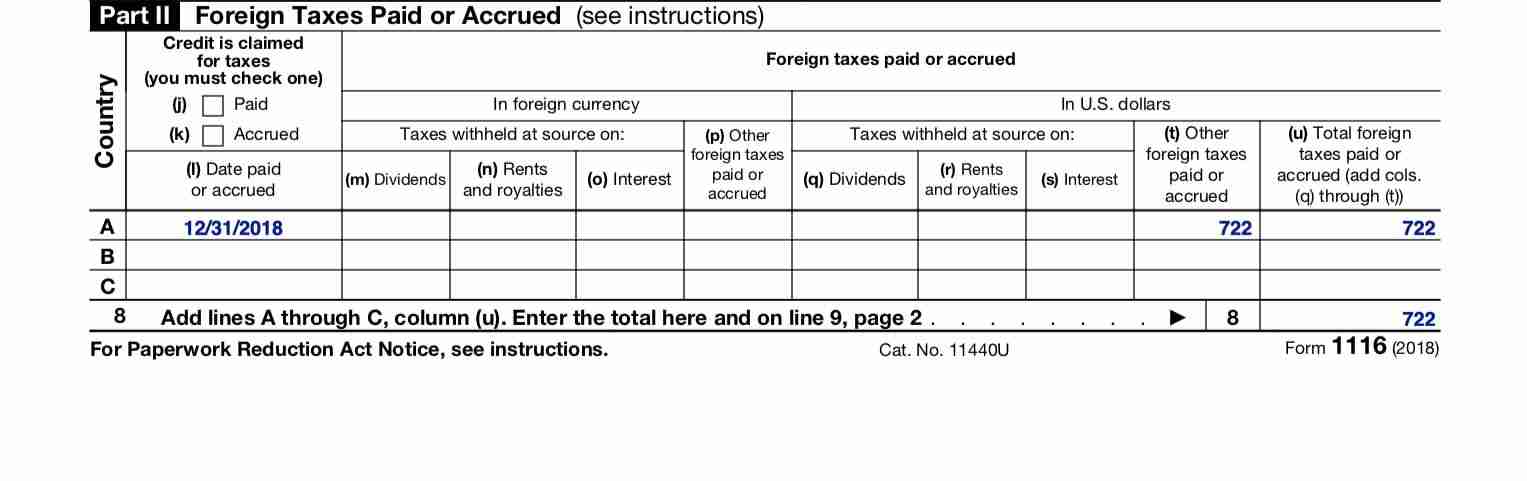
This part will look the same as with the previous form. The amount of taxes paid for this category of income is the only difference here.
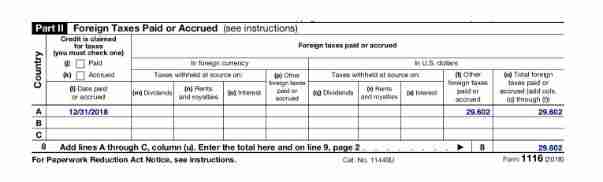
The taxes may be accrued or paid, depending on your accounting method.
One important thing is that if you choose the “accrued” box for the accrued taxes, you will have to credit foreign taxes in the year they accrue in all future returns. The date usually falls at the end of the calendar year. There are some exceptions here, like with the Dual status returns. In such a case, the date is used as the last calendar day the taxpayer is considered as a US citizen (the day of renunciation). More about this topic you can find here
The tax paid/accrued is reported underline A since the income in Amy’s case comes only from one foreign country.
Line A(t) will be the place where the amount of foreign taxes is reported. As we have the amounts that are already converted in USD. The method is the same for the Passive Category income.
Step 4. Complete Part III. Computation of information.
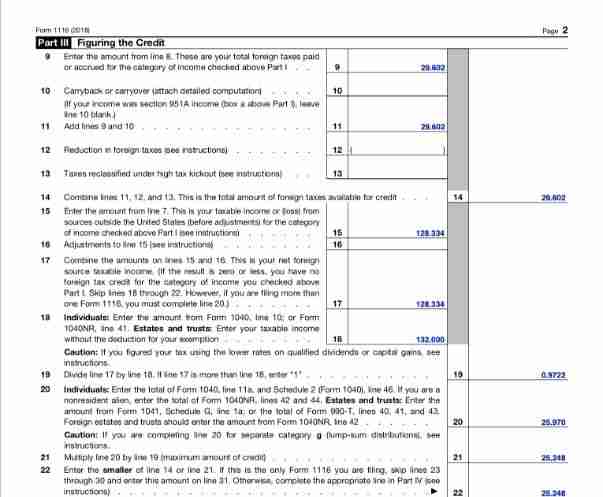
Reported in previous parts of the form. From line 9 to line 20 there is information about taxes paid/accrued which have been transferred from Part II.
- Line 10 indicates potential carryback of carryovers from prior years. Mentioned in Tax Tip 2, but in Amy’s case, there aren’t any.
- Line 12 will indicate the reduction in foreign taxes. This usually occurs when the Foreign Earned Income Exclusion is claimed along with the Foreign Tax Credit.
- Line 15 reflects the calculation from Part II, line 7.
- Line 18 shows the taxable income calculated but dividing standard deduction from gross income of all sources.
- Line 20 represents the taxes imposed for both general and passive income.
- Line 22 shows a portion of US tax for General Category income
Step 5. Complete Part IV.
This part represents the information about the separate parts III. Like we have the situation with Amy. We are preparing two forms 1116, and therefore two different computations in Part III of the forms. The amount of tax credit that has been utilized to offset US tax owing is divided by the sourcing: taxes from general and taxes from passive income.
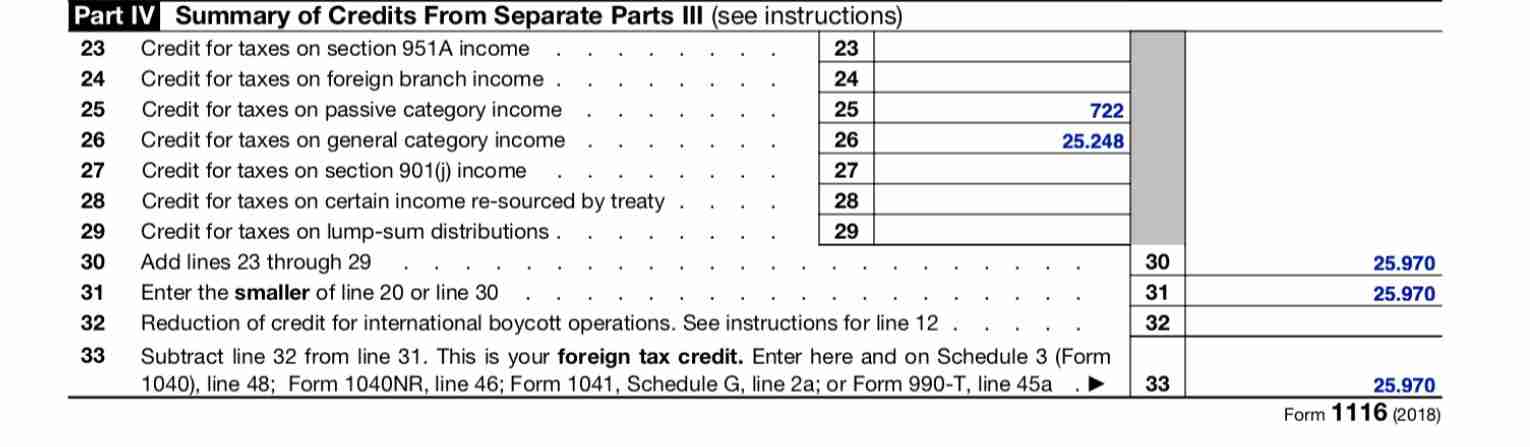
The same method is used when preparing Form 1116 Foreign Tax Credit for some other category income (In Amy’s situation, Passive Category Income). In the following pictures, we’ll show the computations of the Passive income.
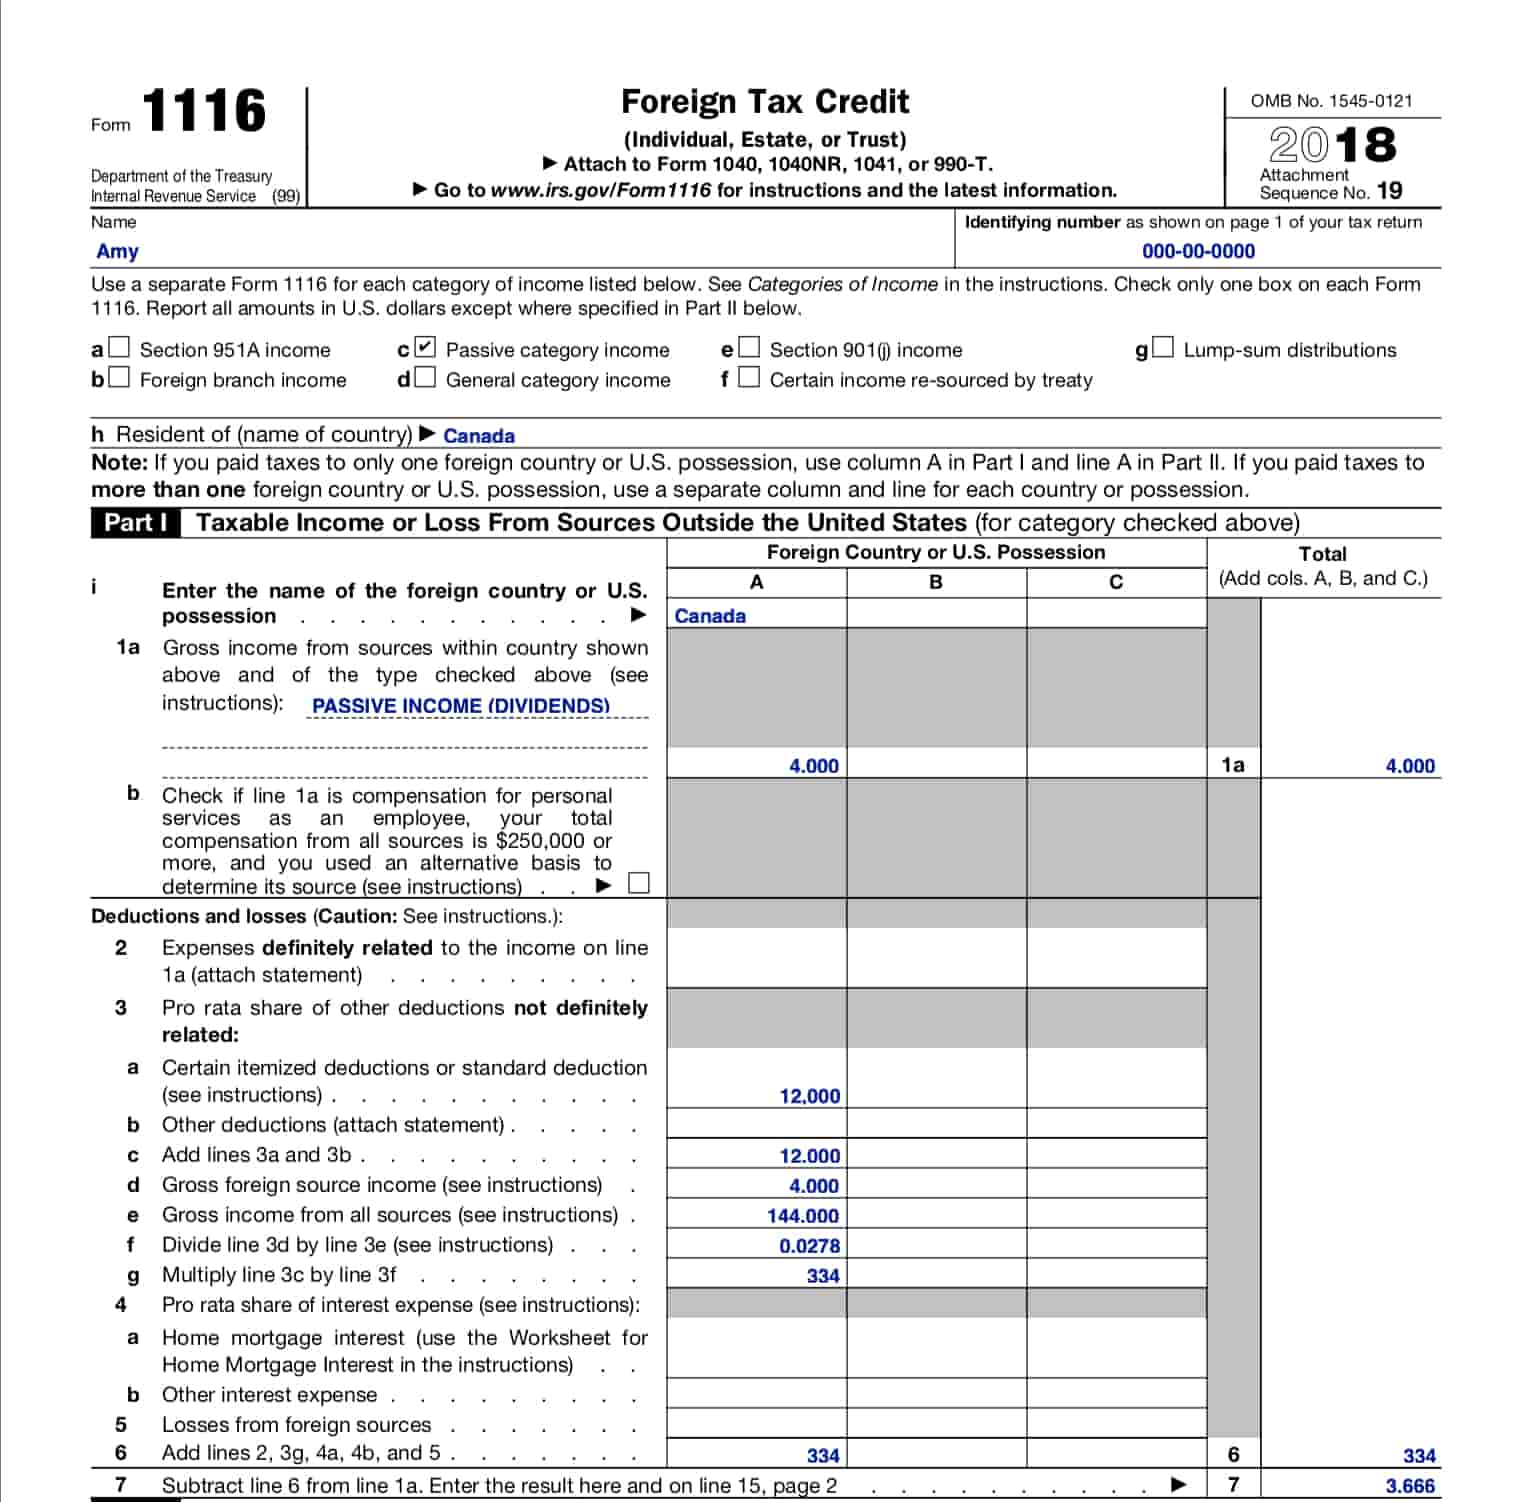
Part II
Part II will look the same as with the previous form. The only difference will be the amount of taxes paid for this category of income.
Part III and Part IV of the form will reflect the computation of passive income. Including the ratio of passive income/standard deduction, which is significantly lower comparing to general income/standard deduction ratio. The portion of US taxes imposed on passive income will be allocated accordingly.
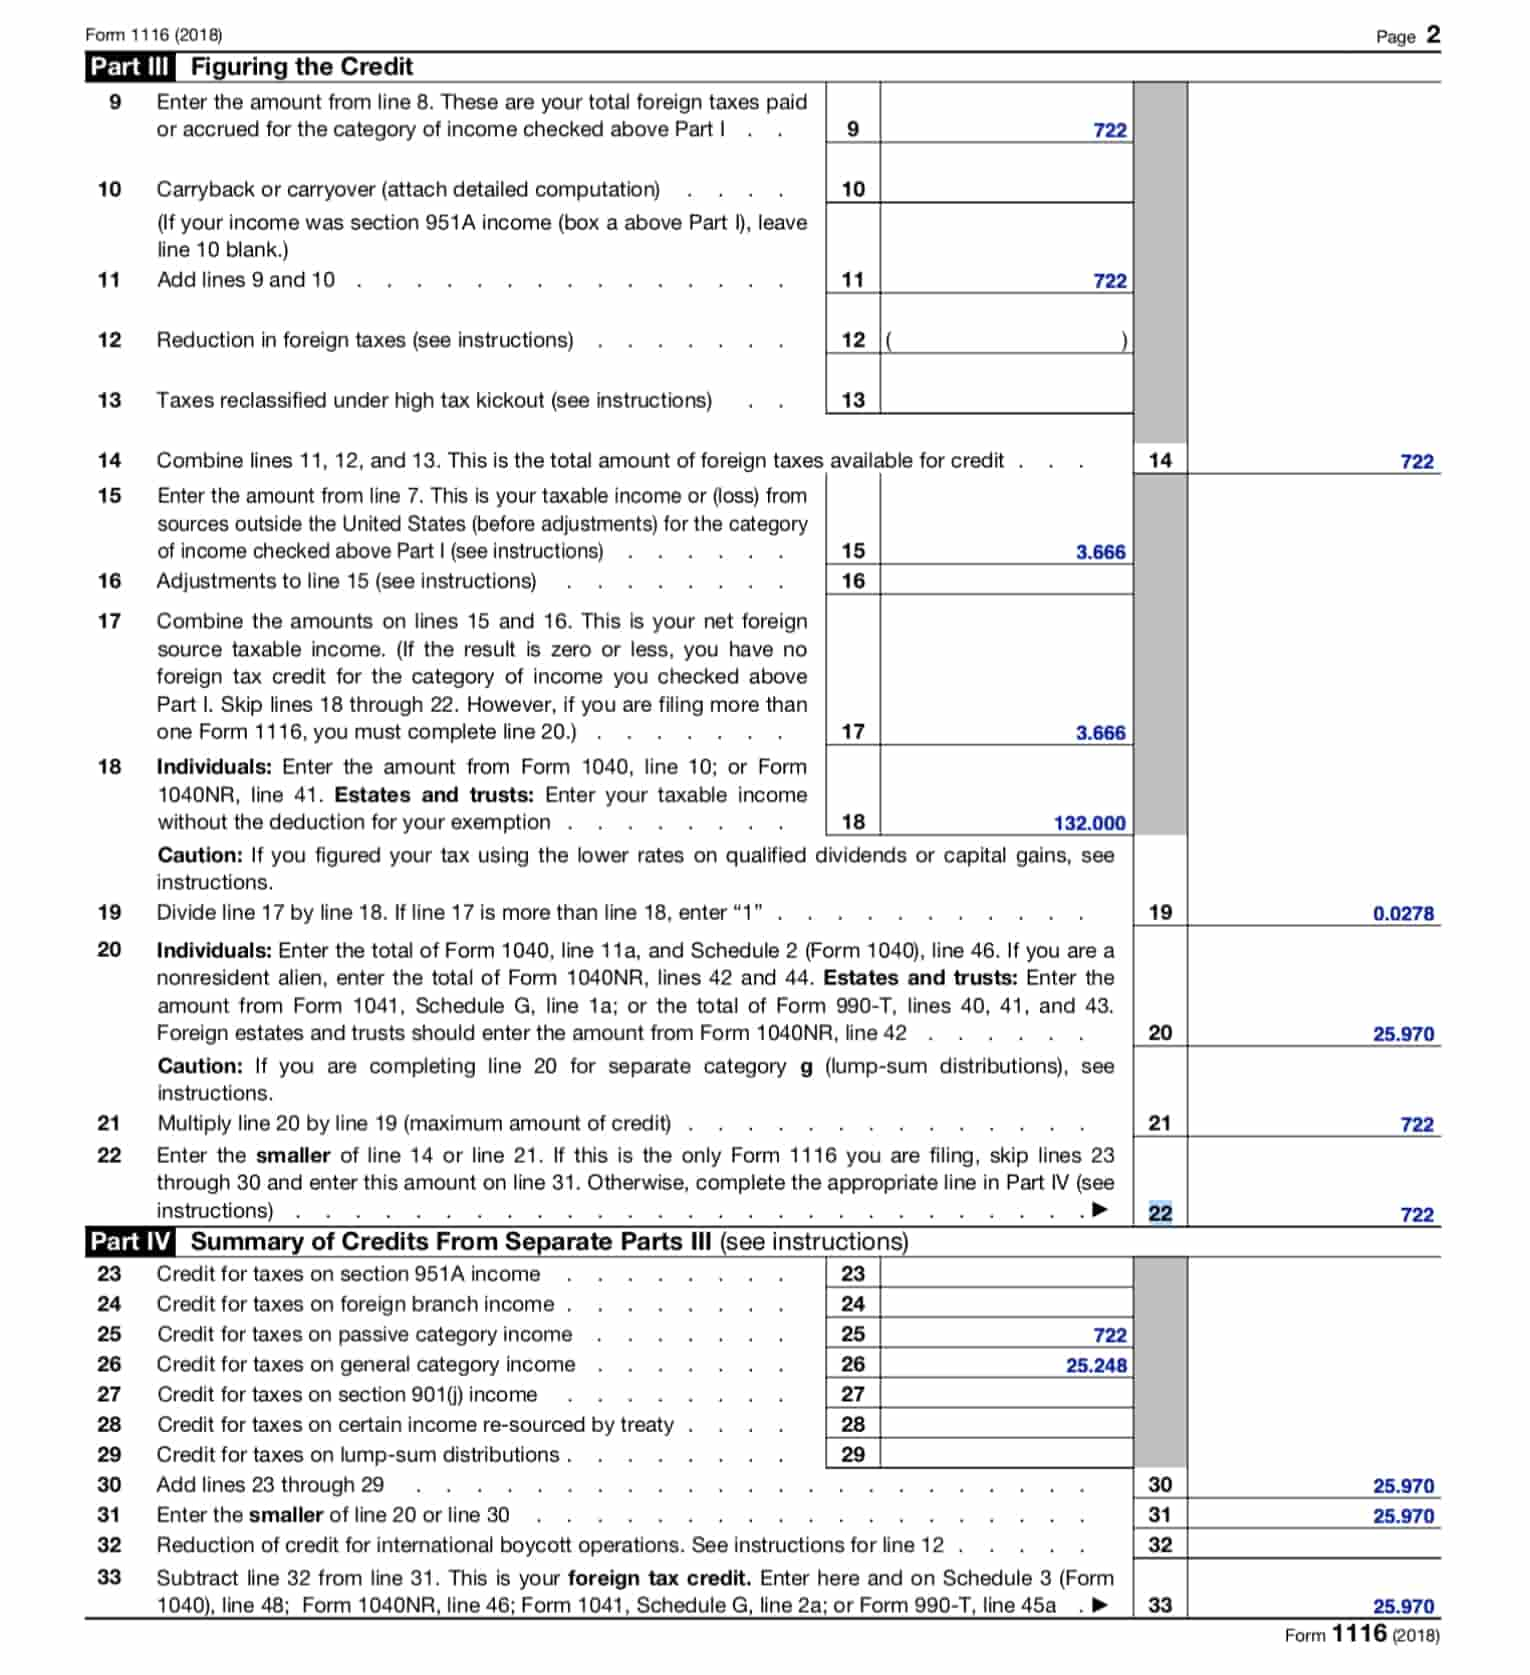
Since the foreign taxes paid on passive income has covered the entire portion of US taxes imposed on passive income, Part IV of the Form 1116 Foreign Tax Credit will be empty.
Since the Foreign taxes paid on General income were higher than the imposed tax on the 1040 tax return, an excess of the credit will be considered as the amount eligible for a carryover. About which we wrote earlier in this article. If necessary, that amount (US$ 4,354) can be utilized to offset the tax owing in the following tax year(s).
In Amy’s case, utilizing form 1116 Foreign Tax Credit over the Foreign Earned Income Exclusion is a better decision. Considering that the FEIE would cover only the first $120,000 of the earnings, while the passive income will be taxed regularly.
Can You Return to the FEIE After Switching to the FTC?
If you formally revoke the Foreign Earned Income Exclusion, you generally cannot claim it again before the sixth tax year following the revocation unless you receive IRS approval.
Using the Foreign Tax Credit during those years does not remove this restriction. Expats should therefore compare the long-term effects before switching from the FEIE to the FTC.
Is Form 1116 Easier to Qualify for Than Form 2555?
Form 1116 does not require you to meet the Physical Presence Test or Bona Fide Residence Test. It also does not ask for the detailed travel, visa, and foreign-housing information required by Form 2555.
However, Form 1116 requires detailed information about your foreign income, the countries where the income arose, foreign taxes paid or accrued, income categories, related deductions, currency conversions, and any available carryovers.
Expats should keep their foreign tax returns, income statements, tax-payment records, and exchange-rate calculations to support the credit.
If you have any questions or assistance with your filing, don’t hesitate to contact us. We’re here to help!


